Beginner's Mutual Fund Guide
Is saving money alone enough to build long-term wealth?
Most people work hard, earn money and save a portion of their monthly income. But simply keeping money aside may not always be enough to meet long-term financial goals, particularly when inflation reduces the purchasing power of money over time.
Consider saving ₹5,000 every month. Your contribution would be ₹60,000 in one year and ₹6 lakh over 10 years, before considering any interest or investment return. If you invest regularly in an appropriate investment product, the money may have an opportunity to grow over time.
Mutual funds are one way to participate in financial markets. They are market-linked investments, however, and neither capital nor returns are guaranteed.
1. What is a mutual fund?
A mutual fund pools money from multiple investors and invests it in financial instruments such as company shares, government securities, corporate bonds and money-market instruments, according to the scheme's stated investment objective.
The portfolio is managed by an Asset Management Company (AMC) under the applicable regulatory framework. Investors receive units based on the applicable Net Asset Value (NAV).
A simple example
If you invest ₹5,000 and the applicable NAV is ₹50, you receive 100 units, before applicable transaction-level adjustments. If the NAV later rises, the value of those units rises; if the NAV falls, their value falls.
2. Why do people invest in mutual funds?
Professional fund management
The scheme is managed by a professional team according to its stated investment objective. This does not remove investment risk.
Diversification
Some schemes spread investments across multiple securities. Diversification can reduce dependence on a single security, but cannot eliminate market risk.
Small investment amounts
Many schemes allow investors to start with relatively small amounts, subject to the scheme's minimum investment requirements.
Systematic investing
A SIP can help investors contribute at regular intervals and develop an investment habit.
Different investment categories
Equity, debt, hybrid and other categories have different objectives, risks and characteristics.
Information and disclosures
Investors can review scheme documents, portfolio disclosures, NAV, expense ratio and the Riskometer.
3. What is SIP and how does it work?
SIP stands for Systematic Investment Plan. It is a method of investing a fixed amount in a mutual fund scheme at regular intervals, such as monthly or quarterly.
For example, an investor may choose a monthly SIP of ₹1,000, ₹2,000, ₹5,000 or another amount permitted by the scheme. The amount should be chosen according to the investor's financial capacity and goals.
Understanding rupee cost averaging
When the NAV is lower, the same SIP amount generally purchases more units; when the NAV is higher, it purchases fewer units. This is known as rupee cost averaging. It spreads purchases across different market levels, but it does not guarantee profits or prevent losses.
4. The power of compounding: Why does time matter?
Compounding means that investment gains, when retained and reinvested, can themselves generate further gains over time. Regular contributions and potential investment growth may work together over a long investment period.
Starting early can give an investment more time to compound. However, compounding is a mathematical process, not a promise that a market-linked investment will earn a particular return. Actual outcomes depend on market performance and the scheme.
SIP Illustration
What could a ₹5,000 monthly SIP become in 10, 20 and 30 years?
The following values are hypothetical calculations using assumed annualised return rates. They are not actual fund performance, forecasts or promised returns.
| Period | Invested | At 8% | At 10% | At 12% |
|---|---|---|---|---|
| 10 years | ₹6 lakh | ₹9.15 lakh | ₹10.24 lakh | ₹11.50 lakh |
| 20 years | ₹12 lakh | ₹29.45 lakh | ₹37.97 lakh | ₹49.46 lakh |
| 30 years | ₹18 lakh | ₹74.52 lakh | ₹1.13 crore | ₹1.75 crore |
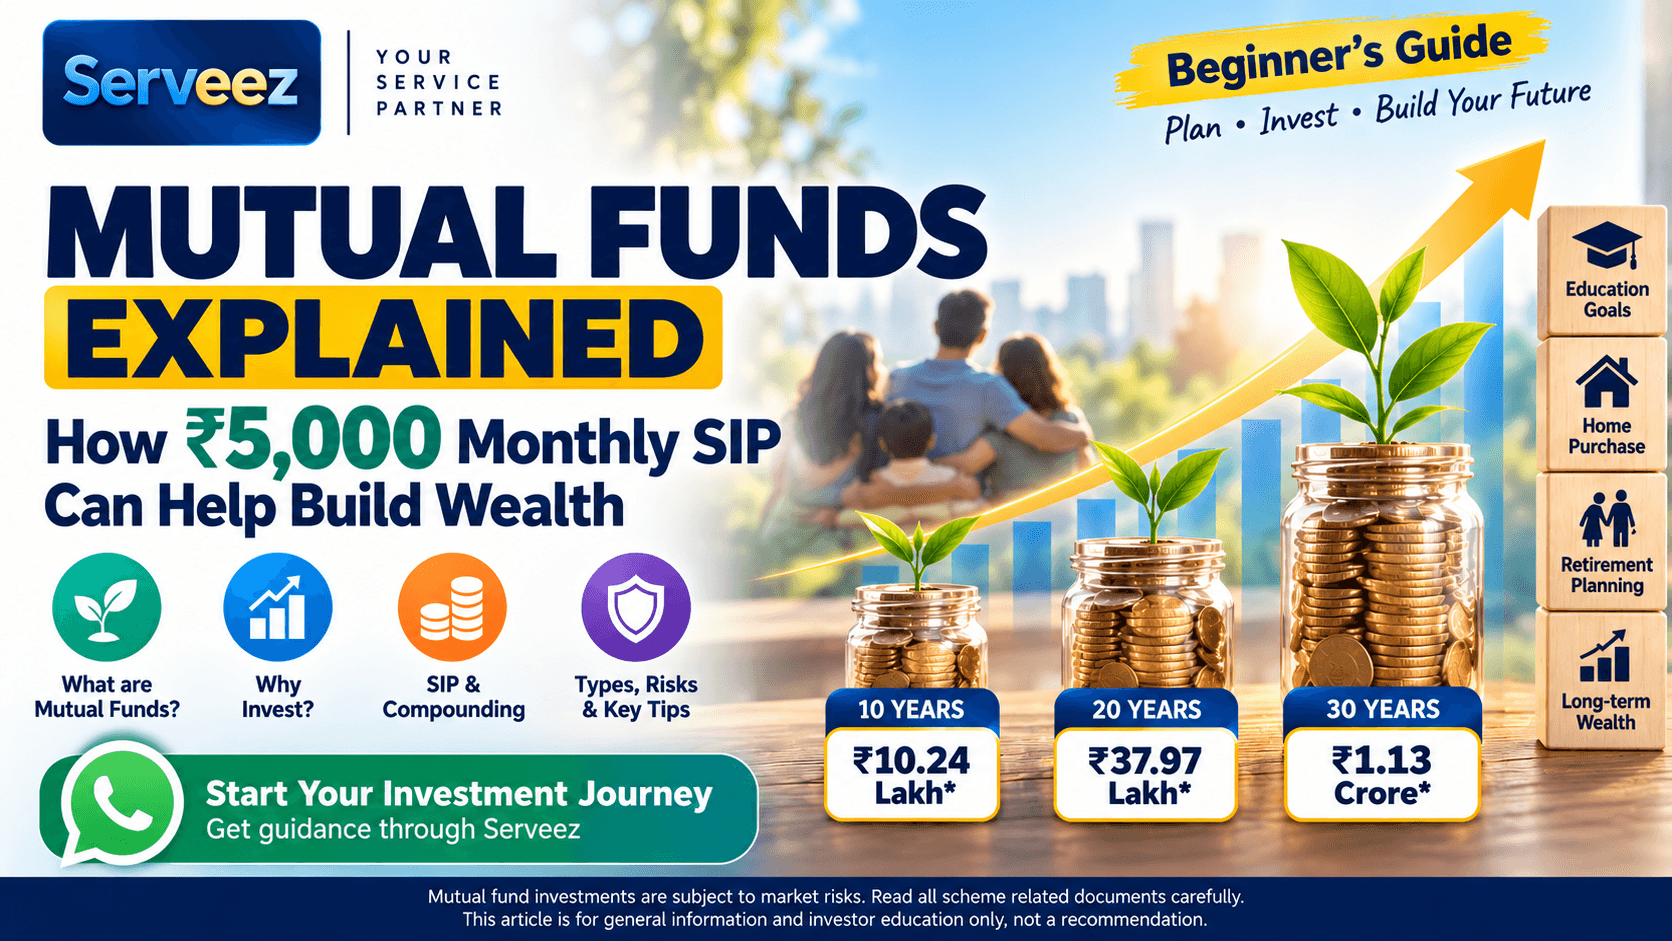
At the illustrative 10% assumption, a ₹5,000 monthly SIP totals ₹6 lakh contributed over 10 years, ₹12 lakh over 20 years and ₹18 lakh over 30 years. The corresponding hypothetical future values are approximately ₹10.24 lakh, ₹37.97 lakh and ₹1.13 crore.
Calculation assumptions: instalments are invested at the end of each month; the monthly rate is the assumed nominal annual rate divided by 12; the SIP remains ₹5,000 throughout; no annual SIP increase is assumed. Figures are rounded. Taxes, exit loads and investor-specific charges are excluded. Actual returns fluctuate and may be lower, including negative.
5. What are the different types of mutual funds?
Equity mutual funds
These schemes invest primarily in company shares. They may be considered for long-term capital appreciation, but can experience significant market fluctuations. Categories include large-cap, mid-cap, small-cap, flexi-cap, multi-cap, index, sectoral and thematic funds.
Debt mutual funds
These schemes invest primarily in fixed-income instruments such as government securities, corporate bonds and money-market instruments. They carry risks including interest-rate risk, credit risk and liquidity risk; they are not the same as bank fixed deposits.
Hybrid mutual funds
These schemes invest in a combination of equity and debt instruments. The allocation depends on the scheme category and investment objective.
Index funds
These funds aim to track a specified market index, subject to tracking error and expenses. Their performance may differ from the index.
ELSS funds
Equity Linked Savings Schemes are equity-oriented mutual funds with a statutory three-year lock-in for each investment. Tax benefits, if available, depend on applicable tax law and the investor's eligibility and tax regime.
Do not select a scheme only because it recently delivered high returns. Consider the scheme objective, investment horizon, risk level, costs and your own financial situation.
6. What financial goals can mutual funds potentially support?
Depending on the scheme, time horizon and risk tolerance, mutual funds may be considered as part of planning for:
- Children's higher education
- Long-term wealth accumulation
- Retirement planning
- A future home purchase
- Building a financial corpus
- Other medium- and long-term goals
Not every mutual fund is suitable for every goal. Money needed in the near term should not automatically be exposed to the volatility of equity-oriented schemes. Match the investment category to the time available and your ability to bear losses.
7. What are the risks of mutual fund investments?
Market risk
Changes in equity and debt markets can cause the value of mutual fund units to rise or fall.
Credit risk
A debt scheme may be affected if an issuer fails to meet payment obligations or its credit quality deteriorates.
Interest-rate risk
Changes in interest rates can affect the market value of fixed-income securities.
Liquidity risk
Some securities may be difficult to sell quickly, particularly during stressed market conditions.
Concentration risk
Schemes focused on a particular sector, theme or limited set of securities may experience greater fluctuations.
Understand the SEBI Riskometer
Mutual fund schemes display a Riskometer to help investors understand the scheme's risk level. The six levels are Low, Low to Moderate, Moderate, Moderately High, High and Very High. Review the current Riskometer and scheme documents before investing. A higher risk level does not guarantee higher returns.
8. How should a beginner start investing?
- 1.Define your financial goal.
- 2.Decide how long you can remain invested.
- 3.Understand your ability to tolerate investment losses.
- 4.Complete the applicable KYC requirements.
- 5.Understand the mutual fund category and scheme objective.
- 6.Read the Scheme Information Document (SID) and Key Information Memorandum (KIM).
- 7.Review the benchmark, portfolio, Riskometer, expense ratio and exit load.
- 8.Understand the difference between Direct and Regular plans.
- 9.Choose an investment amount that fits your financial capacity.
- 10.Review your investments periodically in line with your goals.
Do not invest borrowed money or money required for essential expenses simply because someone promises attractive returns.
9. Direct Plan vs Regular Plan: What should investors know?
Mutual fund schemes generally offer Direct and Regular plans. A Direct Plan is purchased directly by the investor without a distributor. A Regular Plan is purchased through a mutual fund distributor and its expense structure includes distribution-related costs.
The underlying portfolio of the same scheme is generally the same, but the expense ratio and resulting NAV can differ. Investors should understand the plan type, costs, services and applicable distributor remuneration before choosing.
10. Common mutual fund myths
Myth: Mutual funds always generate profits.
Fact: Mutual funds are market-linked products. Investors may make profits or incur losses.
Myth: SIP guarantees returns.
Fact: SIP is an investment method, not a guaranteed-return product.
Myth: A fund with a lower NAV is cheaper or better.
Fact: NAV alone does not determine whether a scheme is attractive or suitable.
Myth: A fund that performed well last year will perform well next year.
Fact: Past performance does not guarantee future results.
Myth: Every investor should invest in equity mutual funds.
Fact: Investment choices should reflect individual goals, time horizon and risk tolerance.
11. Start with discipline, not return expectations
Building wealth is not necessarily about investing a very large amount at once. It involves understanding your financial goals, developing a savings habit, choosing suitable investment products and giving them an appropriate amount of time.
A ₹5,000 monthly SIP may look small today. Over 10, 20 or 30 years, regular investing and potential compounding may create a meaningful corpus. But actual outcomes depend on market conditions, scheme selection, expenses and investment duration. There is no guaranteed return.
Serveez Mutual Fund Distribution Assistance
Understand the investment process before you begin.
Serveez provides mutual fund distribution assistance and general information about the investment process. You can contact us for information about SIP registration, KYC-related assistance, mutual fund categories, Direct and Regular plans and scheme documents.
💬 Enquire about Mutual Fund SIPsOfficial investor information
- SEBI Investor – Understanding Mutual Funds for basic information about mutual funds.
- SEBI – Financial Education Booklet for investor education.
- AMFI – Introduction to Mutual Funds for mutual fund basics.
- AMFI – Risks in Mutual Funds for information about investment risks.
- AMFI – Circulars for Mutual Fund Distributors for distributor-related guidelines and updates.
Distributor identification
Chaitanya Kumar Neelisetti
AMFI-registered Mutual Fund Distributor
ARN: 347140